Showing posts with label Presentation. Show all posts

Friday, 25 July 2025

Aminex AGM Signals Acceleration:

Aminex AGM Signals Acceleration: CH‑1 Before Pipeline, Phase 2 Plans, and Market-Ready Momentum

For me, this year’s Aminex AGM marked a fundamental shift—not just in tone, but in tempo.

For the first time in years, the Board spoke with conviction and clarity. No ambiguity. No hedging. Just a clear message: Ntorya is entering execution mode, and the drill is coming before the pipeline is complete!


๐Ÿ”ฉ “CH‑1 Will Be Drilled Before the Pipeline Is Completed”

No hesitation. No caveats. That is now the base case.

The Board confirmed that all parties—TPDC, ARA, Aminex, and the Tanzanian government—are aligned and urgently pushing to get CH‑1 drilled. PURA’s involvement has been specifically to accelerate rig tendering.

Rig tendering is imminent. While a shared rig with M&P is being discussed, other rigs are in the running—and the Board made it clear that M&P’s timeline would be too late (mid‑2026). In other words: the M&P option may just be negotiation leverage.

Bottom Line:

  • TPDC is “pushing like crazy”

  • CH‑1 is on the clock

  • Phase shift confirmed. Execution starts now.


๐Ÿ“ˆ CH‑1 Targeting 50 MMscf/d Flow Rate

The Board corrected the assumption of 20 MMscf/d per well:

“CH‑1 is expected to flow at ~50 MMscf/d.”

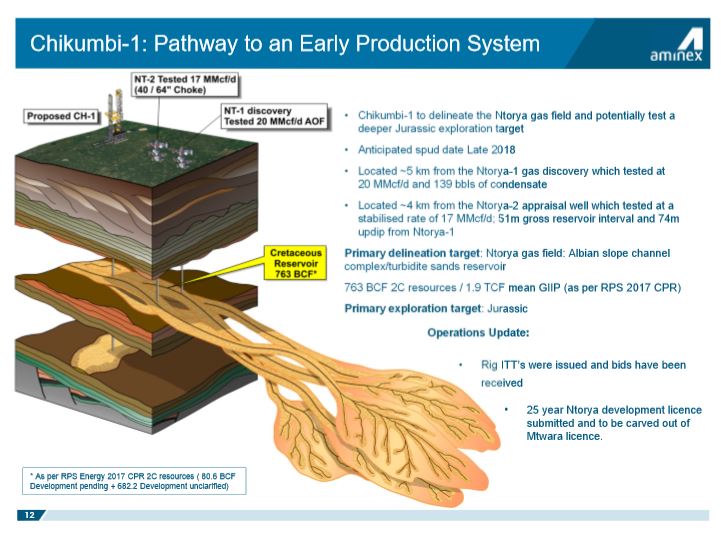
This well targets a thicker section of the reservoir with stacked pays, including Unit 3—making it much higher impact than NT‑2, which flowed 17 MMscf/d under constrained conditions.

A new CPR (Competent Person’s Report) is expected after CH‑1 or Phase 1 drilling, with upgraded reserves, production profiles, and valuation.


๐Ÿ’ง Condensate Could Add +15% to Project Value

The Board confirmed condensate volumes could deliver ~15% additional value—clean margin revenue, possibly hundreds of millions over the field’s life.


๐Ÿ’ธ Gas Pricing Has Built-In Upside

Two key revenue drivers:

  1. Inflation clause built into the GSA

  2. Higher prices for industrial offtake vs. utility rates

With industrial gas demand rising in Tanzania, Aminex could see surprise upside on realised pricing.


๐Ÿ”— ARA Wants Aminex to Stay

Why hasn’t Aminex been bought out or diluted? The Board explained:

  • ARA is happy with 75% and sees value in Aminex’s public listing

  • The listing provides transparency, valuation, and investor reach

  • If ARA wanted Aminex gone, it would’ve happened already


๐Ÿš€ Phase 2 Strategy: 280 MMscf/d or Bust

The operator isn’t stopping at Phase 1:

  • 6 more wells planned

  • Second pipeline to Madimba

  • Expanded processing facility

“140 MMscf/d won’t adequately drain the field. 280 MMscf/d brings reserves into production within the license life.”

This is operator-led strategy, not speculative dreaming. Ntorya is being built as a national energy asset.


๐Ÿฆ Funding Runway + Cash Flow Timing

  • Aminex has used ~50% of its facility, with ~$1.5m available

  • Burn rate: ~$1.5m/year, so fully funded for 12 months

  • First cash flow expected ~September 2026, once the pipeline is commissioned

Payments will be a mix of USD and Tanzanian Shillings.


๐Ÿงพ TPDC to Take 60 MMscf/d Initially

TPDC has committed to 60 MMscf/d of initial offtake, with the rest going to industrial customers. Virtual pipeline, LNG, CNG, mining, manufacturing are all in ARA’s strategy.

Demand is not a concern. Discussions are already underway.


๐Ÿงช NT‑2 Test Still Going Ahead

Despite the focus on CH‑1, the NT‑2 well test is still scheduled before pipeline commissioning. It will confirm deliverability and gas composition (expected 3% CO₂ content—low and manageable).


๐Ÿ“Œ TPDC Back-in Rights Still at 15%

The 15% back-in right has not been exercised yet, and that remains the limit under the PSA. Any change would be procedural and expected.


๐Ÿ” Kiliwani, Nyuni, and Exploration Strategy

  • Kiliwani is on hold, but still has potential. Seismic planned.

  • Nyuni is “too risky” for now. Scale-down and partnership are in progress.


๐Ÿ“ฃ PR Reset and New Valuation Coming

The Board acknowledged past silence and promised a PR reset:

  • Regular updates to resume

  • Journalists engaged

  • New Shard Capital valuation incoming—expected to be more bullish


๐Ÿง  Final Word: It’s Not “If” Anymore

This AGM didn’t just confirm:

  • CH‑1 before pipeline completion

  • 50 MMscf/d flow potential

  • Phase 2 expansion strategy

It changed the tone of the entire project.

We’re not asking if Ntorya will deliver.
We’re asking how fast, how big, and how long we stay invested.


The above report comes thanks to the attendance at the AGM by Prospero 

Thursday, 10 July 2025

Walking a Mile in ARA's Shoes - Strategic Rationale for Retaining Aminex PLC in the Ntorya JV

Here’s a strategic rationale written as if from ARA Petroleum Tanzania’s internal planning team, arguing for maintaining the current JV structure with Aminex PLC, emphasizing the benefits of Aminex’s London market presence:

๐Ÿ“„ Strategic Rationale for Retaining Aminex PLC in the Ntorya Joint Venture

Prepared by: ARA Petroleum Tanzania – Strategic Planning Unit
Date: July 2025


1. Capital Market Access & Optionality

Aminex’s listing on the London Stock Exchange provides the Ntorya JV with indirect access to one of the world’s most liquid and reputable capital markets. This offers multiple strategic advantages:

  • Enhances visibility of the project to institutional and retail investors.

  • Preserves optionality for future fundraising—whether for downstream integration, exploration expansion, or reserve monetisation.

  • Provides a clear public valuation benchmark for our asset base through Aminex’s market capitalization and disclosures.


2. Governance, Transparency & Investor Confidence

The London listing mandates high standards of financial reporting, ESG compliance, and corporate governance. As a result:

  • Aminex strengthens the JV’s perceived integrity and regulatory alignment, both domestically and internationally.

  • Transparent public disclosures de-risk the JV in the eyes of financiers, multilateral institutions, and host governments.

  • Enhanced transparency provides reassurance to the Tanzanian Petroleum Development Corporation (TPDC) and other local stakeholders.


3. Geopolitical Diversification & Host Country Comfort

Retaining a Western-listed partner brings geopolitical balance to the JV, providing:

  • Greater international confidence in the project’s operational structure.

  • A “dual footprint” approach that aligns with host government interests in balancing foreign investment across regions (Middle East, Europe, Africa).

  • Increased credibility with development finance institutions and bilateral aid agencies exploring gas infrastructure support in East Africa.


4. Exit Optionality & Capital Efficiency

Aminex’s presence in the JV:

  • Offers ARA long-term strategic flexibility, including potential monetisation of stakes via reverse takeovers, secondary offerings, or spin-offs.

  • Allows for capital-light development, given Aminex’s cost-carry arrangement and minimal capital exposure during early ramp-up.

  • Keeps ARA’s balance sheet flexible, with the ability to scale operations without assuming full ownership risk at this stage.


5. ESG and Institutional Alignment

Through Aminex, the JV gains exposure to ESG-conscious investor groups and reporting frameworks, including:

  • Task Force on Climate-Related Financial Disclosures (TCFD)

  • UN Sustainable Development Goals (SDGs)

  • Local stakeholder engagement protocols under LSE guidelines

This strengthens the project’s profile among:

  • Sovereign lenders (e.g., AfDB, World Bank)

  • Global investment funds pursuing sustainable energy in Africa

  • Local regulators focused on responsible energy development


Conclusion

Maintaining the current JV structure, with Aminex as a 25% non-operating partner listed on the London Stock Exchange, strategically benefits ARA Petroleum Tanzania in multiple dimensions: capital flexibility, regulatory alignment, stakeholder confidence, and future monetisation. These outweigh any perceived advantages of immediate consolidation. We recommend continuing and deepening the partnership during the upcoming pipeline and production ramp-up phases.

Friday, 23 October 2020

Aminex PLC RNS Announcement - Farm-out completion

Aminex Farm out Completion


23 October 2020

AMINEX PLC (“Aminex” or “the Company”)

Completion of Ruvuma Farm-Out Aminex is pleased to announce the Completion of the Ruvuma Farm-Out. The Company, through its wholly owned subsidiary, Ndovu Resources Limited, has transferred a 50% interest in, and operatorship of, the Ruvuma PSA to ARA Petroleum Tanzania Limited (“APT”).

Monday, 12 October 2020

Aminex PLC - Drewky's List

Congratulations to each and everyone of you, it's been a long time coming but hopefully you will all feel a little better tonight.  It was never in doubt for me although I admit my bottom was begining to twitch over the last few days.

Anyway Good luck to you all. Raise a glass and one day soon we may just well have that party! Here is the updated list and if it helps people to understand where we are then please share.

Wednesday, 19 August 2020

Aminex Unofficial Blog Direction Change


Having not posted on the bulletin boards since July 2019 my personal views apart from limited words on Twitter have been pretty much kept to myself.

However I think it's time I should let my own feelings be known once again, but I'll not be doing it on the lunatic asylums known as the bulletin boards.

Monday, 16 July 2018

Late Night Sneaky Leak Presentation Preview

Expecting the official publication at 7pm by RNS but for all you night owls I've just received a link to sneaky peek

Full article  with images asap

Tuesday, 10 July 2018

The Call for Better Communication

The following presentation was one made by myself to the Aminex Board back in December and the response from the Chairman Brian Hall was as follows...

Friday, 2 February 2018

Aminex The Road Map From Solo Oil & Gas Perspective


The Road is Clearer...
Highlights 2017

Appraisal well Ntorya-2 successfully drilled and tested at a constrained rate of 17 mmscfd;

Significant increase to resources estimates as a result of Ntorya-2, to over 1.34 tcf gross discovered gas in place;

Filed a development plan for the Ntorya Gas Field including an early production scheme;

Thursday, 24 August 2017

5.4.3.2.1.....Aminex Ready For Lift Off


With anticipation building and news due anytime, I’m so looking forward to putting the first of an expected stream of direct Aminex news onto the blog.  It's only been three weeks since the appointments of the new COO and the companies own solicitor were made and just five since collaboration with io GE was announced who themselves, bring possible leveraging of their own parent companies to the party.


During the last five weeks, the share has seen around 50% increase in SP as it has edged

Wednesday, 28 June 2017

1st June 2017 - Porosity - A Horrendous Gas Field

A little study whilst waiting for the updated basin model....

I started here with the basics of Looking for Oil & Gas

It Led me to this "With sandstones, a porosity of 18% or more is usually needed for an economic oil reservoir. Gas flows easier than oil, so as little as 12% porosity may be enough for a gas reservoir"
So off I went to check Page 8 of the recent AGM Presentation
With very limited knowledge it looks to me like we have 20% porosity, so further study was needed and so time to go to university of Alabama for 45 minutes to study porosity logs! (A little heavy but so much interesting stuff and worth the time invested)
The first video starts at 8 minutes 50 seconds...

19th May 2017 - AGM Presentation


Visit Aminex PLC to view full presentation


8th March 2017 - Ntorya-2 Appraisal Presentation


Visit Aminex PLC for full Appraisal Presentation